
Inflation Holds at 3.8% — The Bank of England’s Balancing Act
The UK is moving from emergency policy towards normalisation — a slower, more deliberate cycle where capital efficiency, risk management, and strategic timing will define success.
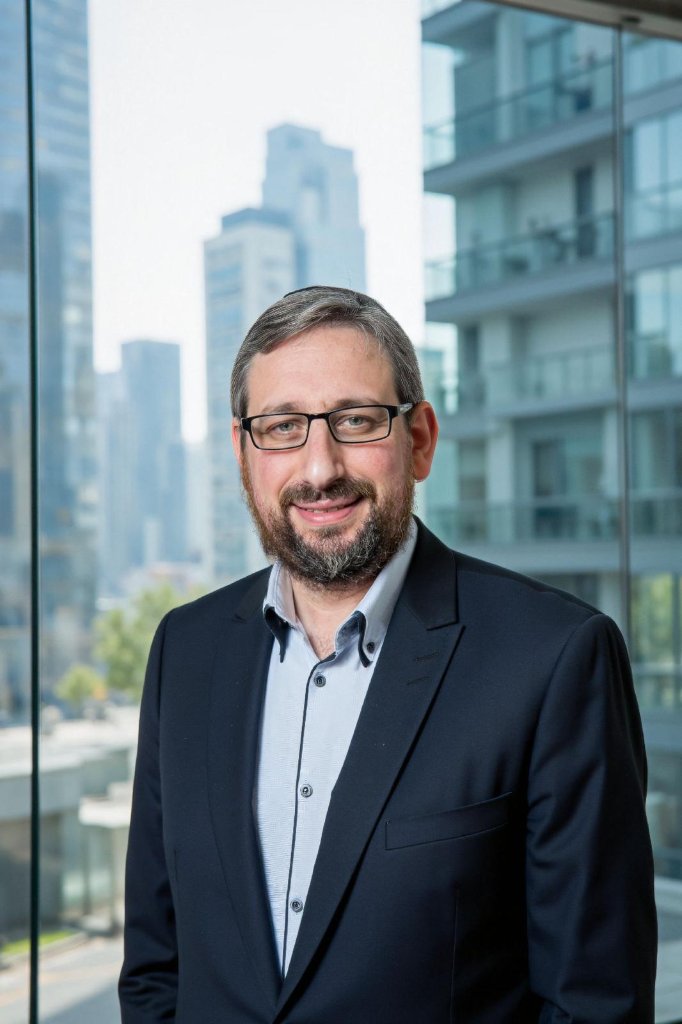
Maxim Cohen
UK inflation remained at 3.8% in September, defying expectations of a fall and highlighting the challenge facing the Bank of England as it tries to tame price pressures without suppressing growth.
While easing food and energy prices provided some relief, services inflation — a core indicator of domestic price stability — held steady at 4.7%, well above the 2% target. This persistence suggests that inflationary momentum within the UK economy remains embedded, driven by wages, supply chain costs, and structural inefficiencies that monetary policy alone cannot resolve.
The Market Response
Markets reacted swiftly. Traders increased bets on a December interest rate cut, pushing two-year gilt yields down to 3.77%. The move reflects growing confidence that the Bank will soon shift from restraint to support. Yet beneath this optimism lies uncertainty: cutting rates too soon risks reigniting the very inflation the Bank has worked to contain.
The Bank’s Monetary Policy Committee (MPC) now finds itself in a precarious position — navigating between the need to encourage growth and the imperative to preserve its credibility on inflation control.
Fiscal Policy and the November Budget
The forthcoming Budget on 26 November will be pivotal. Chancellor Rachel Reeves has signalled fiscal discipline, acknowledging that “people are putting in more and getting less out.” Economists widely agree that a credible fiscal tightening could give the Bank cover to reduce rates safely in 2026.
The interplay between fiscal and monetary policy is now central. Should the Budget combine prudence with targeted investment, the UK could begin to shift from stagnation toward a more stable, productivity-led recovery.
Implications for Borrowers and Investors
For borrowers, the short-term outlook remains constrained, but momentum is shifting. As inflation steadies and yields fall, lending margins may compress, gradually improving affordability through 2026. Challenger banks and private lenders are already recalibrating risk models, preparing for a lower-rate environment.
For investors, the current phase represents an opportunity to accumulate real assets and private credit exposure ahead of the next easing cycle. Those positioned early stand to benefit from the narrowing spreads and valuation uplifts that typically follow a monetary inflection point.
The Financier’s View
September’s data may not mark the end of the inflation story, but it likely signals the beginning of a transition. The UK is moving from emergency policy towards normalisation — a slower, more deliberate cycle where capital efficiency, risk management, and strategic timing will define success.
The Bank of England’s challenge is no longer about controlling inflation at any cost; it’s about restoring equilibrium without undermining confidence. The next chapter of this economic cycle will reward prudence, patience, and informed decision-making.
Maxim Cohen
Principal • The Financier
Official Member of Forbes Finance Council
With over 20 years of experience in global finance, Maxim Cohen facilitates ethical finance across UK, US, and Middle East markets. As a Chartered Member of the Chartered Institute of Securities and Investment and CPA Accountant, he leads the UK Finance Group ecosystem, connecting capital with opportunity worldwide.